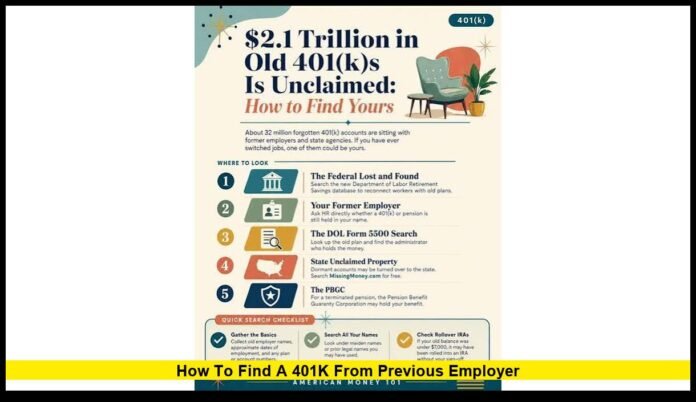
 from a previous employer using retirement search tools, old statements, employer records, and plan administrators.)
Learning how to find a 401(k) from a previous employer can help you recover track of retirement savings you may have forgotten after changing jobs. Many Americans leave workplace retirement accounts behind when they move to a new company, relocate, or lose contact with a former employer. These accounts may continue to hold investments even years after employment ends.
Fortunately, several methods can help you locate an old 401(k). You can contact your former employer, search for retirement plan records, use federal retirement search tools, and check whether your account moved to another financial institution.
The key is to gather accurate employment information and follow the appropriate steps to verify your account. Once you locate the plan, you can confirm your balance and explore the options available for managing your money.
Why Do People Lose Track of Old 401(k) Accounts?
A 401(k) is a workplace retirement savings plan that allows eligible employees to contribute part of their paychecks toward retirement. Employers may also provide matching contributions or other contributions under the plan’s rules.
When you leave a job, your retirement account does not necessarily close. Depending on the plan’s terms and your account balance, you may be able to leave the money invested, transfer it to another eligible retirement account, or receive a distribution.
People often lose track of these accounts for several reasons.
- They change jobs without transferring their retirement savings.
- They move to another state and stop receiving account statements.
- They forget which financial institution manages their old plan.
- Their former employer changes its name or ownership.
- They lose access to their previous work email account.
- The business closes or stops operating.
- They overlook retirement paperwork after leaving a job.
Workers who have held several jobs throughout their careers may have multiple retirement accounts to investigate.
Start by creating a list of previous employers and approximate employment dates. This simple step can make it easier to identify the correct retirement plan.
1. Start by Contacting Your Previous Employer
Your former employer is often the best place to begin when searching for an old 401(k).
Contact the human resources department, benefits team, or payroll department. Explain that you previously worked for the company and want to determine whether you still have retirement benefits associated with your employment.
Ask for the name of the company’s retirement plan administrator. This organization may be a brokerage firm, retirement services provider, insurance company, or another financial institution.
Before contacting the employer, gather any information that could help identify your employment records.
Useful details include:
- Your full name while working for the company.
- The approximate dates you were employed.
- Your former department or work location.
- Your employee identification number, if available.
- Any previous name connected to your employment records.
If the company has merged with another business, ask whether the successor organization now manages the retirement plan.
For a company that has closed, try to identify its former benefits administrator or the organization responsible for its retirement plan.
Never send sensitive personal information to an unverified email address or telephone number. Use an official contact method and follow the administrator’s identity verification requirements.
2. Search Your Personal Email and Financial Records
Old emails can provide valuable clues about a forgotten retirement account.
Open the personal email account you used while employed and search for terms such as “401(k),” “retirement benefits,” “account statement,” “employer match,” “vesting,” and “rollover.”
Look for messages containing enrollment confirmations, investment statements, account access instructions, and notices about retirement plan changes.
An old statement may identify the retirement provider, plan name, account number, and customer service information.
If you locate a provider’s name, visit its official website and use the account recovery process. You may need to confirm your identity before the company allows access.
You should also check old pay stubs and employment documents. Pay statements may show deductions for retirement contributions, while benefits paperwork may identify the plan you joined.
Remember that an old statement does not establish your current balance. The account could have changed in value, incurred fees, or moved to another institution.
Request updated information before deciding whether to transfer or withdraw the funds.
3. Search the Federal Retirement Savings Lost and Found Database
The federal Retirement Savings Lost and Found Database is a useful starting point for people who cannot remember where their previous employer kept their retirement savings.
The database was created under the SECURE 2.0 Act of 2022 and launched in December 2024. It helps eligible individuals identify reported retirement plans connected to their employment history.
To begin, visit the official federal Retirement Savings Lost and Found website.
Follow the instructions to verify your identity through Login.gov. The process requires the identification information and documentation specified by the service.
After verification, you can search for reported retirement plans associated with your Social Security number.
If the search identifies a plan connected to your former employment, review the available details and contact the listed plan administrator.
The administrator can explain whether the plan still holds benefits for you and what steps you must complete to access your account.
There are limitations to this resource. It does not cover every retirement arrangement, and some information may be incomplete or outdated. It also does not directly distribute retirement funds.
A missing search result does not prove that your account no longer exists. Continue checking employer records and other retirement search resources if necessary.
4. Use Retirement Plan Search Resources From the Department of Labor
The U.S. Department of Labor provides resources to help workers investigate missing retirement benefits.
Its Employee Benefits Security Administration, known as EBSA, helps people understand their rights under many private-sector retirement plans.
If you know the employer’s name but cannot identify the retirement provider, search for available plan information through the department’s retirement resources.
Use the company’s legal name whenever possible. Some businesses operate under a public-facing brand that differs from the name used in official retirement records.
Review any relevant plan information and identify the organization responsible for administering the benefits.
If you cannot determine where your account is held, contact an EBSA benefits adviser for guidance. Advisers can explain available resources and help you understand how to pursue missing benefits.
You can reach EBSA at 1-866-444-3272.
Keep a record of your conversations, including the names of representatives, dates of contact, and any instructions they provide.
5. Investigate Retirement Plans From Businesses That Closed
Finding a 401(k) can be more challenging when a former employer has permanently closed.
However, a business closure does not automatically mean its retirement savings have disappeared. Responsibility for a plan may have passed to another administrator or been handled through a formal termination process.
The Department of Labor’s Abandoned Plan Program addresses certain individual-account retirement plans abandoned by employers or administrators.
Search its Abandoned Plan Database using the former company’s name.
If you identify a matching plan, review the available information and contact the qualified termination administrator responsible for the plan.
The administrator can explain how former employees may establish their claims to any remaining retirement benefits.
Not every closed employer appears in this database. If you find no match, search for a successor business, contact the original plan provider, or seek assistance from EBSA.
Having your employment dates and former employer’s legal name available can make this process more efficient.
6. Check Retirement Registries and State Unclaimed Property Records
Another way to investigate missing retirement savings is to search for unclaimed benefits.
The National Registry of Unclaimed Retirement Benefits allows people to investigate certain retirement benefits reported as belonging to former employees.
Follow the registry’s current instructions and review its privacy practices before providing personal information.
If you find a possible match, contact the responsible organization to verify the details.
You can also search official state unclaimed property databases in states where you previously lived or worked.
In certain circumstances, funds associated with a former retirement account may appear in a state unclaimed property system. However, not every missing 401(k) ends up in such a database.
A search may produce no results even when a retirement account exists. Use these resources alongside your former employer’s records and federal retirement search tools.
Be cautious of companies that promise to recover retirement funds for an upfront fee when you may be able to investigate the account through free resources.
7. Find Out Whether Your Retirement Account Changed Providers
Your former 401(k) may have moved to a different financial institution after you left your job.
Employers sometimes change retirement plan administrators to obtain different services or investment options. Corporate mergers and acquisitions can also lead to changes in plan management.
If you remember the original provider, contact its customer service department and ask whether the plan moved to another institution.
If the company no longer manages the plan, request the successor provider’s contact information.
You can also ask your former employer whether it changed retirement administrators after your departure.
Once you identify the current provider, follow its account recovery process and request an updated statement.
This step is particularly important when old website addresses no longer work or your previous account login has become inactive.
8. Use Annual Retirement Plan Filings to Identify the Administrator
If you remember your employer but cannot identify its retirement provider, annual retirement plan filings may help.
Many private-sector retirement plans file Form 5500 or a related annual report. These filings can contain the plan’s name, sponsor details, and information about organizations involved in administering it.
Search the available records using the employer’s legal name and the approximate years you worked there.
Compare the information across different years if the company changed retirement providers.
The filings may help you identify the appropriate organization to contact, but they generally do not provide a complete record of your individual account balance.
After finding a potential plan, contact its administrator and explain that you want to verify your former employee retirement benefits.
9. Verify Your Account and Current Balance
Once you identify a possible 401(k), the next step is to confirm that the account belongs to you.
The plan administrator may request identification, employment information, and other details to establish ownership.
After completing verification, ask for a current account statement.
Review the following information carefully:
- Account balance: Confirm the amount currently held in the account.
- Investment holdings: Identify the funds or investments in which your savings are invested.
- Fees: Review administrative expenses and investment costs.
- Vesting: Determine whether employer contributions are fully vested.
- Beneficiaries: Check that your designated beneficiaries are accurate.
- Distribution rules: Ask what options are available under the plan.
Your own contributions generally belong to you. Employer contributions, however, may be subject to vesting requirements, which determine how much of those contributions you retain when leaving employment.
If the balance differs from what you expected, ask the administrator to explain the account history, any fees, and any previous distributions.
10. Decide What to Do With Your Old 401(k)
After finding your retirement account, you can evaluate the available options.
| Option | Important consideration |
|---|---|
| Keep the money in the former employer’s plan | Availability depends on the plan’s rules and your account balance. |
| Roll the funds into a new employer’s 401(k) | The receiving plan must accept the rollover. |
| Transfer the funds to an IRA | An eligible rollover can consolidate retirement savings. |
| Take a distribution | Taxes and potential additional penalties may apply. |
Compare investment choices, fees, withdrawal restrictions, and tax implications before making a decision.
A direct rollover can move eligible funds from one retirement arrangement to another without paying the money to you first.
If an eligible distribution is paid directly to you, federal income tax withholding generally applies to the taxable portion. You typically have 60 days to complete a qualifying rollover, subject to applicable rules and exceptions.
Withdrawals made before age 59½ may trigger an additional 10% federal tax unless an exception applies. Ordinary income taxes may also apply to taxable distributions.
Because retirement withdrawals can have long-term financial consequences, consider speaking with a qualified tax professional before making a major decision.
Frequently Asked Questions
Can I find an old 401(k) without paying a fee?
Yes. You can start by contacting former employers, reviewing old account statements, and using available federal retirement search resources. These steps can help you investigate an account without paying a private recovery company.
Can I use my Social Security number to locate an old 401(k)?
The federal Retirement Savings Lost and Found Database allows eligible individuals to search for reported retirement plans after completing identity verification. The plan administrator must confirm whether benefits remain available.
What happens to my 401(k) when I change jobs?
Your retirement savings generally remain subject to your former plan’s rules. Depending on the circumstances, you may be able to keep the money in the plan, roll it over, or take a permitted distribution.
Can I find a 401(k) from an employer that no longer exists?
Yes, it may still be possible. Search the abandoned retirement plan database, investigate federal retirement records, and contact benefits advisers if you cannot identify the responsible administrator.
Does the federal retirement search database show my exact balance?
The database helps identify reported retirement plans. Contact the administrator directly to confirm ownership, obtain your current balance, and learn about distribution options.
How long does it take to locate an old retirement account?
The time varies. An account may be straightforward to locate when you have old statements, but searches involving closed businesses or outdated records can require additional investigation.
Conclusion
Finding a forgotten 401(k) can help you take control of retirement savings accumulated throughout your working life. Start with your previous employers and personal records, then use federal search tools and other retirement resources if the account remains difficult to locate. Once you find it, verify the balance and carefully review your options before moving the money.
Have you tracked down a forgotten retirement account from a previous job? Share your experience in the comments to help others learn how to find their old 401(k) savings.