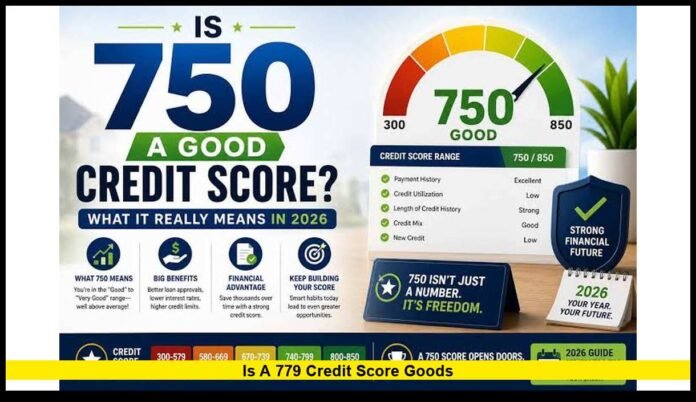

Is a 779 credit score good? Yes, a 779 credit score is considered very good under the standard FICO scoring system used by many lenders in the United States. This score can help consumers qualify for competitive credit cards, mortgages, auto loans, and personal loans. However, lenders also examine income, debt obligations, credit history, and other financial details before approving an application or determining its interest rate.
For American consumers, a score in this range represents a strong foundation for borrowing. It sits near the upper end of the very good category and just below the exceptional range in the FICO system. Although a high score can create valuable financial opportunities, borrowers still need to compare lending offers, manage outstanding balances, and maintain consistent payment habits.
Understanding how credit scores work can help consumers make better decisions when financing a home, purchasing a vehicle, or choosing a new credit card.
Key Points Summary
- A 779 FICO score falls within the very good credit category.
- FICO scores generally range from 300 to 850.
- Strong credit can improve access to competitive borrowing terms.
- Lenders consider more than a credit score when reviewing applications.
- Low credit card balances and on-time payments help maintain a healthy profile.
- Reaching an 800 score is possible, but it is not necessary to qualify for many competitive financial products.
What Does a 779 Credit Score Mean?
A credit score is a numerical estimate of how likely a person is to repay borrowed money based on information in their credit history. Financial institutions use these scores alongside other information to evaluate applications and manage lending risk.
Under the standard FICO scoring scale, a 779 score falls into the very good category, which covers scores from 740 through 799. The exceptional category begins at 800 and extends to 850.
Here is how the main FICO score categories compare:
| FICO Score | Rating |
|---|---|
| 800–850 | Exceptional |
| 740–799 | Very good |
| 670–739 | Good |
| 580–669 | Fair |
| 300–579 | Poor |
A score of 779 therefore indicates a favorable credit position. It is considerably above the threshold for good credit and may help a borrower access lending opportunities that are less available to people with lower scores.
These categories are general guidelines rather than universal lending rules. Each financial institution sets its own approval standards, and different scoring models can classify the same numerical score differently.
How Does a 779 Score Compare With the U.S. Average?
A 779 FICO score is above the national average reported in recent credit-score data. Experian reported an average FICO Score of 713 in 2025, placing a 779 score 66 points above that benchmark.
This comparison suggests that a borrower with a 779 score has a stronger score than the average American consumer represented in that data.
However, national averages do not determine whether an individual qualifies for a loan. A lender may approve someone with a lower score if the rest of the application meets its requirements. Another applicant with a higher score could face difficulties because of substantial debt, insufficient income, or other underwriting concerns.
Credit scores also change over time. Updated account balances, payment records, credit applications, and other reported information can affect a consumer’s score. The number displayed by a financial app may differ from the score a lender obtains when reviewing an application.
Why a 779 Credit Score Matters When Borrowing
A strong credit score can influence several parts of the borrowing process. Lenders may use it to assess risk, determine eligibility, and help establish the interest rate or other terms offered to an applicant.
A borrower with very good credit may receive more competitive offers than someone with a weaker credit profile. Nevertheless, the precise benefit depends on the financial product, the lender, and the applicant’s circumstances.
For consumers planning a major purchase, the value of a strong score often becomes clearest when comparing actual loan offers.
Mortgage Applications and Home Financing
A 779 score can strengthen a mortgage application because it falls within a favorable FICO range. Depending on the mortgage program and the lender’s pricing rules, the score may help a homebuyer qualify for competitive financing.
Mortgage approval involves more than creditworthiness. Lenders generally evaluate income, employment, existing debts, available assets, down payment, and the property’s details.
The debt-to-income ratio is especially important. This measurement compares a borrower’s monthly debt obligations with gross monthly income. Even a strong credit score may not overcome a debt burden that exceeds a lender’s permitted limits.
Mortgage programs also have different eligibility requirements. Conventional mortgages, government-backed loans, and other financing arrangements can apply different underwriting standards.
Homebuyers should therefore compare lenders rather than assuming that every institution will offer identical rates. Closing costs, discount points, lender fees, and loan terms can affect the overall cost of purchasing a home.
Auto Loans and Vehicle Financing
Consumers with strong credit may have an advantage when applying for auto financing. A 779 score can help support an application for competitive interest rates, depending on the lender and the vehicle being purchased.
The final offer can also depend on the size of the down payment, the amount borrowed, the repayment term, and the applicant’s income and existing obligations.
Buyers should compare the annual percentage rate, total interest, loan duration, and total amount payable. A longer repayment period can make monthly payments appear more affordable while increasing the total cost of financing.
Dealer promotions also deserve careful review. Some advertised rates apply only to particular vehicles, loan terms, or highly qualified applicants. A strong credit score does not automatically guarantee eligibility for every promotional offer.
Obtaining preapproval from a bank or credit union can give buyers another offer to compare with dealership financing.
Personal Loans and Other Borrowing Options
A 779 score can improve a consumer’s position when applying for an unsecured personal loan. Some lenders reserve their most competitive rates for applicants with strong credit profiles.
However, personal loan providers may also examine income, debt obligations, loan purpose, and recent credit activity. Approval and pricing vary among financial institutions.
Before accepting a loan, consumers should review the annual percentage rate, origination fees, repayment schedule, and late-payment charges. They should also consider whether the borrowing is necessary and whether the monthly payments fit their budget.
A high credit score can improve access to financing, but it does not make every available loan financially worthwhile.
Credit Cards and Premium Rewards
A strong credit profile can help consumers qualify for a wider selection of credit cards. These may include cash-back cards, travel rewards products, and cards designed for applicants with excellent credit.
Card issuers still consider several factors when reviewing applications. Income, existing balances, recent credit inquiries, and the applicant’s overall financial obligations can influence the decision.
Consumers should evaluate annual fees, rewards structures, interest rates, introductory offers, and redemption restrictions before applying. A premium card may provide valuable benefits, but those benefits should justify its costs.
Paying the statement balance in full each month can also help cardholders avoid purchase interest when their account terms provide a grace period. Rewards rarely justify carrying expensive revolving debt.
What Determines Your Credit Score?
Credit scoring models analyze information in credit reports to estimate lending risk. The precise calculations depend on the model, but payment history, credit utilization, account age, new credit, and credit mix are important considerations in the standard FICO framework.
Payment History
Payment history is a major factor in FICO scoring. Consistently paying bills on time helps establish a record of responsible credit management.
Late payments can hurt a score, particularly when they become significantly overdue. Their impact depends on factors such as severity, recency, and the rest of the credit history.
Automatic payments and reminders can reduce the risk of missing due dates. Consumers should check their accounts regularly to ensure payments process correctly.
Credit Utilization
Credit utilization measures revolving balances against available credit limits. Lower utilization generally supports a healthier credit profile.
For example, a consumer with $15,000 in total credit card limits and $1,500 in reported balances has 10% utilization.
Keeping balances low can help, particularly before applying for a mortgage or another major loan. Paying down debt can also reduce interest expenses and improve monthly cash flow.
Consumers do not need to maintain a balance or pay interest to build credit. Using credit responsibly and paying on time is a better long-term approach.
Length of Credit History
The age of credit accounts can contribute to a credit score. A longer history provides more information about how a borrower manages financial obligations.
Closing an older credit card may affect available credit and utilization. The effect on the age-related portions of a score depends on the scoring model and how the account is reported.
Consumers should weigh annual fees, account benefits, and spending habits before closing a card. Keeping an account open solely for its age may not make sense if it creates unnecessary expenses.
New Credit and Credit Mix
Several new applications within a short period can affect a credit profile. Hard inquiries may temporarily lower a score, although the impact varies.
Credit mix also contributes to some scoring models. It can include revolving accounts, such as credit cards, and installment loans, such as auto loans.
Borrowers should not take out unnecessary loans simply to diversify their credit. Managing existing accounts responsibly is more important than acquiring credit they do not need.
How to Maintain or Improve Your Score
Consumers who already have strong credit should concentrate on protecting their financial habits rather than pursuing a perfect number.
Useful steps include:
- Pay all credit obligations by their due dates.
- Keep revolving balances manageable.
- Avoid applications that do not serve a clear purpose.
- Review credit reports for inaccurate information.
- Monitor accounts for unfamiliar transactions.
- Maintain a budget that supports consistent debt repayment.
Someone asking, “is a 779 credit score good” should also understand that a higher score is not the only measure of financial health. Emergency savings, affordable debt payments, and manageable expenses matter when preparing for a major purchase.
An 800 score falls within the exceptional FICO category, but there is no guaranteed method or timeline for moving from 779 to 800. Scores respond to reported information, and improvements can vary from one credit profile to another.
How to Check Your Credit Reports
Consumers can obtain free credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com. Reviewing reports helps identify errors that could affect credit decisions.
Check for unfamiliar accounts, incorrect payment records, inaccurate balances, duplicate entries, and accounts that do not belong to you.
If you find a mistake, dispute it with the relevant credit reporting company and contact the business that supplied the information when appropriate. Accurate reporting matters because scoring models rely on the information contained in credit files.
Checking your own credit report does not lower your credit score. Consumers can also access scores through participating banks, credit unions, and credit card issuers.
Why Different Services May Show Different Scores
A credit score can vary between financial apps because providers may use different scoring models, credit bureaus, or reporting dates.
FICO and VantageScore are separate scoring systems. They can evaluate credit information differently and may assign different numbers or labels to the same consumer.
Lenders also select models suited to particular products. A mortgage lender may use a different scoring approach from an auto lender or credit card issuer.
For this reason, a score displayed in an app should be treated as a useful indicator rather than a guarantee of the score a lender will use. Before submitting a major application, consumers can ask which credit reporting agency and scoring model the lender considers.
Frequently Asked Questions
Is 779 considered excellent credit?
Under the standard FICO scale, 779 falls within the very good category. Exceptional credit begins at 800. Other scoring systems may use different classifications.
Can I qualify for a mortgage with a 779 score?
A 779 score can strengthen a mortgage application, but approval also depends on income, debt-to-income ratio, down payment, assets, property details, and loan requirements.
Can I get a premium credit card with this score?
You may qualify for premium rewards cards, depending on the issuer’s standards and your overall financial profile. No credit score guarantees approval.
Will paying off credit cards increase my score?
Reducing revolving balances can improve credit utilization and may help your score. The actual effect depends on your complete credit profile and the scoring model.
How long does it take to reach 800?
There is no fixed timeline. Changes depend on reported balances, payment history, account information, and other scoring factors.
Does checking my own score hurt my credit?
No. Checking your own score is generally a soft inquiry and does not lower it.
Final Thoughts
A 779 score places consumers in a favorable position under the standard FICO system. It can support access to competitive credit cards and loans, but the strongest financial decisions still require careful comparison of interest rates, fees, repayment terms, and personal affordability. Consistent payments, manageable balances, and accurate credit reports can help preserve a strong credit profile.
How are you maintaining your credit score or working toward your next financial goal? Share your experience in the comments and follow the latest developments in consumer credit.