
Is Resurgent Capital Services legit? Yes, Resurgent Capital Services, L.P. is a real U.S. debt collection and account servicing company. However, its legitimacy as a business does not automatically mean every debt it attempts to collect is accurate, legally enforceable, or connected to the person receiving a letter or phone call.
Resurgent Capital Services helps manage consumer debt accounts, including accounts associated with debt buyers. Its official website provides account management, payment arrangements, and options for consumers seeking to resolve outstanding balances. The company also publishes licensing information and consumer rights disclosures.
The most important distinction is between verifying the company and verifying the debt. Even when a legitimate collector contacts you, you should confirm the account, the original creditor, the amount claimed, and the collector’s authority before paying an unfamiliar debt.
This review explains who Resurgent Capital Services is, why it may contact you, how to check whether a collection notice is genuine, what its public complaint record shows, and what U.S. consumers can do if they dispute an account.
What Is Resurgent Capital Services?
Resurgent Capital Services, L.P. is a consumer debt management and servicing company based in Greenville, South Carolina. It works with debt owners and credit grantors to manage consumer accounts and help resolve outstanding balances.
The company is not simply a name used by scammers. It has an established business profile, an official customer service operation, and publicly listed licensing disclosures.
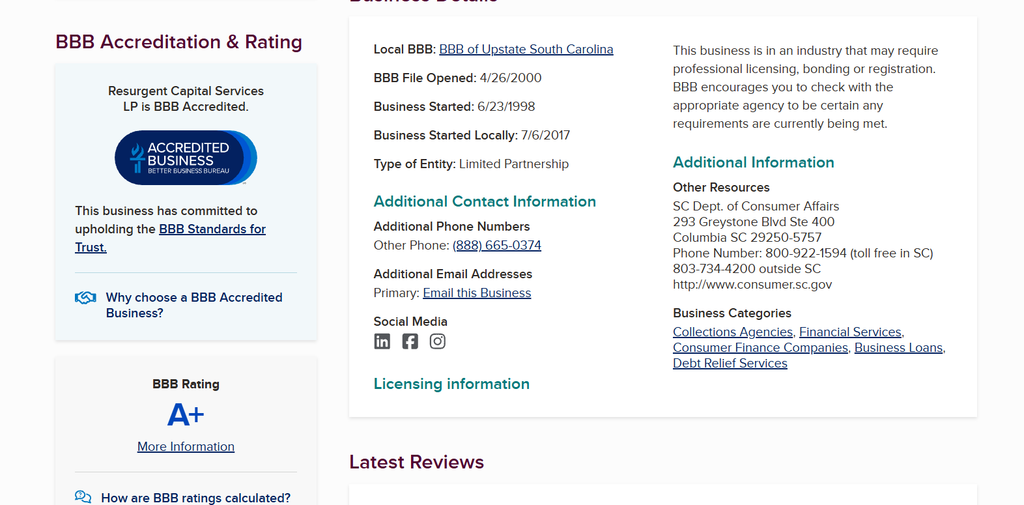
The Better Business Bureau identifies Resurgent Capital Services as a debt collection business. Its profile lists the company’s business start date as June 24, 1998, and shows that it has held BBB accreditation since September 8, 2017. The BBB currently gives the company an A+ rating.
These details support the conclusion that Resurgent is an established business. However, BBB accreditation and ratings do not guarantee that every collection attempt is accurate or that every consumer will have a positive experience.
Resurgent’s role is to manage consumer debt portfolios, which can involve communicating with people about overdue accounts, processing payments, and discussing potential repayment arrangements.
Resurgent Capital Services Contact Information
- Company Name: Resurgent Capital Services, L.P.
- Headquarters: Greenville, South Carolina, United States
- Mailing Address: 55 Beattie Place, Suite 110, Greenville, SC 29601
- Phone Number: 1-888-665-0374
- Official Website: Resurgent.com
- Business Type: Debt collection and account servicing
- Related Company: LVNV Funding LLC
- Customer Service: Contact the company to inquire about an account, verify a debt, discuss payment options, or submit a dispute.
- Consumer Complaints: Consumers can contact the Consumer Financial Protection Bureau or their state attorney general if they believe a debt collector has violated applicable laws.
Why Is Resurgent Capital Services Contacting You?
If Resurgent Capital Services has called you, sent you a letter, or appeared on your credit report, it may be attempting to collect or service a consumer debt.
There are several reasons this might happen.
1. A debt may have been sold to a new owner
Creditors sometimes sell delinquent accounts to companies that purchase outstanding debt. When ownership changes, the new owner may hire a separate company to manage the account and communicate with the consumer.
Resurgent Capital Services may handle these responsibilities on behalf of a debt owner.
2. Resurgent may be servicing an LVNV Funding account
One important relationship involves LVNV Funding LLC, a debt buyer associated with Resurgent’s account servicing operations.
Resurgent Receivables explains that it outsources the management of its portfolio of accounts to Resurgent Capital Services. Consumers may therefore encounter Resurgent while dealing with an account owned by a separate debt purchasing company.
This arrangement helps explain why the name on a collection letter may differ from the original bank, credit card issuer, or lender.
3. An account may have been transferred between companies
A debt can pass through different businesses during its collection history. The original creditor might no longer manage the account directly.
If Resurgent contacts you about a transferred account, ask for the original creditor’s name, the current owner, and information establishing the account’s history.
4. The contact could involve an error or mistaken identity
Legitimate companies can have inaccurate account information. A collection notice might relate to someone with a similar name, an account already paid, an identity theft incident, or a debt that you dispute.
A genuine company name does not prove that the person receiving the notice owes the stated balance.
Is Resurgent Capital Services a Scam?
Resurgent Capital Services itself is an established company, but scammers can impersonate legitimate debt collectors.
That distinction matters when you receive an unexpected call, text, email, or letter claiming to come from Resurgent.
A scammer might copy a company’s name, use a similar email address, or direct consumers to a fraudulent payment page. Someone could also misuse information about a real debt to pressure a consumer into sending money.
You should independently verify the company and the account before making a payment.
Look for these warning signs:
- The caller refuses to identify the collection company or provide a mailing address.
- The person demands immediate payment without explaining the debt.
- The caller threatens arrest or claims you will be jailed for failing to pay an ordinary consumer debt.
- The person demands payment through gift cards, cryptocurrency, or another suspicious method.
- The caller refuses to provide written information about the account.
- The payment website or contact details do not match independently verified company information.
- The person asks for sensitive financial information before establishing a legitimate reason for the request.
These warning signs do not automatically prove fraud, but they justify additional verification.
The Consumer Financial Protection Bureau advises consumers to request the collector’s name, company name, address, telephone number, and information about the debt. You can also check with your state attorney general or the relevant state regulator.
The safest approach is to verify Resurgent through independently located company information rather than relying exclusively on the phone number or payment link in an unexpected message.
What Does the Better Business Bureau Say About Resurgent Capital Services?
The Better Business Bureau provides useful information about a company’s business history, accreditation, rating, and reported customer complaints.
Resurgent Capital Services’ Greenville, South Carolina, profile lists an A+ BBB rating and accreditation. It also identifies the business as a manager and servicer of consumer debt portfolios.
However, the company’s complaint record is an important part of the overall picture.
The BBB complaint page for its Greenville profile reported 382 complaints over the preceding three years, including 113 during the preceding 12 months, when checked for this review.
Those figures should be interpreted carefully. Complaint totals can change, and the number of complaints alone does not establish that every allegation is valid. The BBB also notes that published complaint information may not include every complaint received.
Consumers may report issues involving billing, account balances, communications, payment processing, or disagreements over whether a debt belongs to them.
Before deciding whether to trust a debt collector, consider both its verified business identity and the nature of the complaint record.
An A+ rating is not a guarantee that the company never makes mistakes. Similarly, complaints do not establish that every account it services is incorrect.
The most relevant question for an individual consumer remains whether the specific debt is valid and whether the company is handling it lawfully.
Does Resurgent Capital Services Have the Proper Licenses?
Debt collection licensing requirements vary by state. Some states require collection agencies to hold specific licenses, register with a regulator, or meet additional compliance requirements.
Resurgent publishes a licensing and consumer disclosure page that lists state-specific information.
Its published disclosures include a California collection agency license number and licensing information for certain other jurisdictions. The company also identifies its National Multistate Licensing System identification number as 2301 on its official website.
These disclosures are useful indicators that the company operates within a regulated industry. However, a license listed on a company website does not independently establish that every license remains active or that every activity complies with the law.
If you want to verify a particular license, check the relevant state regulator’s official records. Confirm that the legal business name matches the company contacting you and that the license covers the activity in question.
This step is particularly important if you live in a state with specific debt collection requirements.
How to Verify Whether a Resurgent Debt Is Real
If Resurgent Capital Services says you owe money, take the following steps before paying.
Step 1: Read the collection notice
Check the creditor’s name, the account number, the amount claimed, and the information explaining your right to dispute the debt. Compare these details with your financial records.
Step 2: Identify the original creditor
Determine which bank, lender, or credit card company originally issued the account. If another company now owns the debt, ask for the current creditor’s identity and the information needed to understand the transfer.
Step 3: Request debt validation
If you do not recognize the account or believe the amount is wrong, send a written dispute or request for additional information. Keep a copy of your letter and proof of delivery.
Step 4: Check your financial records
Review old statements, payment confirmations, account closure records, and credit reports. These records can help you identify a paid balance, an unfamiliar account, or an incorrect amount.
Step 5: Decide how to respond
If the debt is valid, review your payment options and obtain the terms in writing. If you dispute it, follow the applicable dispute process instead of paying simply because the collector contacted you.
What Are Your Rights When Resurgent Contacts You?
U.S. consumers have important protections under the Fair Debt Collection Practices Act (FDCPA) and related federal regulations. State laws may provide additional protections.
The precise protections available depend on the type of debt, the collector’s role, and the circumstances of the contact.
Your right to debt validation
Debt collectors generally must provide specified validation information during their initial communication or within five days of that communication, subject to legal exceptions.
The information generally identifies the creditor, the amount of the debt, and how to dispute it.
Your right to dispute a debt
If you send a written dispute within the 30-day validation period, the collector generally must stop collection of the disputed debt until it sends the required verification or a copy of a judgment.
You can dispute a debt because you do not recognize it, believe the amount is incorrect, already paid it, or believe the collector has contacted the wrong person.
Follow the deadline and instructions in your validation notice. Missing the deadline does not automatically mean that you legally owe the debt, but it can affect the specific protections available under the validation process.
Protection against harassment
Covered debt collectors cannot use threats, abusive language, or unlawful harassment to collect a debt. They also cannot make false or misleading representations.
Federal rules generally restrict telephone calls before 8 a.m. or after 9 p.m. in the consumer’s local time, subject to applicable rules and exceptions.
Limits on disclosure to other people
Debt collectors generally face restrictions on discussing your debt with third parties. There are limited exceptions, such as certain communications with attorneys or efforts to locate a consumer.
Protection against misleading threats
A collector cannot lawfully threaten action it cannot legally take or misrepresent the consequences of nonpayment.
For example, a threat of arrest simply because you have an unpaid consumer debt is a serious warning sign.
These protections do not automatically cancel a valid debt. They regulate how covered debts may be collected and what information collectors must provide.
Can Resurgent Capital Services Sue You?
A consumer may worry that a collection letter will lead to a lawsuit.
The answer depends on the account, the applicable law, the company’s role, and whether a legal claim remains available.
A debt collector or debt owner may pursue a lawsuit to collect an enforceable debt when the law permits it. A collection letter alone, however, does not mean that a lawsuit has been filed or that a court has ruled against you.
You should distinguish between three situations:
- A collection notice: A request to resolve an outstanding balance.
- A lawsuit: A formal legal proceeding that requires a response under the applicable court rules.
- A judgment: A court decision that may establish liability and authorize additional collection remedies.
If you receive court papers, do not ignore them. Read the documents carefully, identify the court and case number, and respond by the deadline. Consider contacting a consumer law attorney or legal aid organization.
You may have defenses involving ownership of the debt, the amount claimed, mistaken identity, prior payment, or the statute of limitations.
A lawsuit’s existence does not establish that the allegations are true. Likewise, assuming that an old debt cannot lead to legal action can be risky without checking the applicable law.
Can Resurgent Collect an Old Debt?
Yes, an old debt may still be the subject of collection activity, but the legal options depend on the circumstances.
The statute of limitations generally limits the time available to file a lawsuit to collect a debt. The relevant period varies by state and debt type, and the rules can depend on the contract and other legal details.
A debt that has passed the applicable limitation period is commonly described as time-barred.
In many circumstances, collectors may still contact consumers about time-barred debts, although state laws can impose additional restrictions. A collector generally cannot sue or threaten to sue to collect a time-barred debt where that action is prohibited by law.
Be careful before acknowledging an old debt or making a payment. In some states, certain actions can restart or affect the limitation period.
Before agreeing to a payment arrangement for an old account, verify the date of the last payment, the applicable limitation period, and the legal consequences of your proposed action.
If a collector has filed a lawsuit over an old debt, seek legal guidance promptly. You may need to raise the statute of limitations as a defense rather than assume the court will apply it automatically.
Does Resurgent Capital Services Affect Your Credit Score?
A debt associated with Resurgent Capital Services may affect your credit report, depending on the account’s reporting status and the applicable credit reporting rules.
When a debt becomes delinquent, the original creditor may report information to credit bureaus. A later transfer or sale of the account can introduce additional reporting considerations.
However, not every collection account is reported in the same way, and not every account appearing on a credit report is necessarily accurate.
If you discover an unfamiliar Resurgent-related account, review the entry carefully.
Check the following details:
- The creditor or debt owner identified in the entry.
- The reported balance.
- The account’s dates and status.
- Whether the account belongs to you.
- Whether the same debt appears more than once in a misleading way.
- Whether payments or other account changes have been reflected accurately.
You can dispute inaccurate information with the relevant credit reporting agency and the company that supplied the information. Provide supporting records where available.
If the account resulted from identity theft, explain that in your dispute and consider using the appropriate identity theft reporting and recovery procedures.
Do not assume that paying a collection account will automatically remove it from your credit report. Ask about the specific reporting treatment and obtain any settlement or reporting promises in writing.
How Can You Contact Resurgent Capital Services Safely?
Resurgent’s official website lists 1-888-665-0374 as its customer service and payment telephone number. The company also provides an online account portal for reviewing eligible accounts and managing payments.
Before sharing personal information, independently confirm that you are using the company’s genuine contact channels.
If you receive an unexpected payment demand, do not rely exclusively on a link in a text message or email. Navigate to the company’s official website independently and compare the contact information.
When speaking with a representative, ask for:
- The account number or another appropriate account identifier.
- The name of the original creditor.
- The identity of the current debt owner.
- An itemization of the balance.
- Information about the account’s payment history.
- Instructions for disputing the debt.
- Written confirmation of any proposed settlement or payment arrangement.
Record the date of your communication and retain copies of any correspondence. If a representative makes a settlement offer, make sure the written agreement clearly explains the amount, due date, and whether the payment resolves the entire account or only part of it.
Avoid sharing passwords, verification codes, or unnecessary financial information with an unverified caller.
What Should You Do If Resurgent Is Collecting a Debt You Don’t Owe?
If Resurgent Capital Services contacts you about a debt that is not yours, respond carefully rather than assuming the issue will disappear.
First, identify the reason for the error. The account could belong to another person, contain incorrect identifying information, reflect a disputed transaction, or involve identity theft.
Next, send a written dispute explaining the problem. Include enough information to identify the account, but avoid sending unnecessary sensitive information.
Ask the company to investigate and provide the appropriate verification. If you are within the 30-day validation period, sending the dispute in writing can trigger the collector’s obligation to pause collection until it provides the required response.
Keep copies of the notice, your dispute, and any response. If the company continues to report inaccurate information, dispute the entry with the credit reporting agencies involved.
You can also submit a complaint to the Consumer Financial Protection Bureau or contact your state attorney general if you believe a debt collector has violated applicable law.
If you suspect identity theft, consider reviewing your credit reports and taking appropriate steps to protect your identity.
If you receive a court summons, seek legal advice immediately. A written dispute sent to a collection company does not replace the need to respond to a lawsuit.
FAQs
Is Resurgent Capital Services legit?
Yes. Resurgent Capital Services, L.P. is an established U.S. debt servicing and collection business. Its verified business presence does not establish that every debt it handles is valid.
Is Resurgent Capital Services a debt collector?
Yes. The company manages and services consumer debt portfolios and may contact consumers about outstanding accounts.
Why is Resurgent contacting me about a credit card?
It may be servicing an account for a debt owner after the original creditor transferred or sold the debt. Request information identifying the original creditor, current owner, and amount claimed.
Is Resurgent Capital Services connected to LVNV Funding?
Yes. Resurgent provides servicing and account management for debt portfolios associated with LVNV Funding and other debt owners. The specific ownership and servicing arrangement depends on the account.
Should I pay Resurgent Capital Services immediately?
Do not pay an unfamiliar debt solely because a collector demands payment. Verify the account, review the balance, and understand your dispute rights first. If you owe the debt, evaluate the available payment options and obtain settlement terms in writing.
Can I dispute a debt from Resurgent Capital Services?
Yes. You can dispute a debt you believe is incorrect or does not belong to you. A written dispute within the applicable 30-day validation period generally requires the collector to pause collection until it provides the required verification.
Does an A+ BBB rating mean Resurgent is completely trustworthy?
No. The rating is one piece of information about the business. It does not guarantee that every collection attempt is accurate or that the company has never received complaints.
Can Resurgent Capital Services remove a collection from my credit report?
The outcome depends on whether the reporting is accurate and what correction or removal obligations apply. Dispute inaccurate information and request an investigation. Do not assume that paying a valid debt guarantees removal.
What should I do if someone pretends to be Resurgent?
Do not send money or disclose sensitive information until you verify the caller independently. Use contact information obtained through the company’s official website, and report suspected fraud to the appropriate authorities.
Final Verdict: Is Resurgent Capital Services Legit?
Resurgent Capital Services is a legitimate, established debt servicing and collection company, with a public business profile, published licensing disclosures, and consumer account management services. Its relationship with debt owners such as LVNV Funding also explains why some consumers receive collection notices under the Resurgent name rather than the name of their original creditor.
Nevertheless, a legitimate company does not automatically mean a particular debt is correct or enforceable. Consumers should verify the account, check the balance, review their rights, and dispute inaccurate claims before making payment arrangements.
If Resurgent contacts you, focus on the evidence rather than the pressure to pay quickly. Keep written records, verify the debt owner, and seek qualified legal help if a dispute or lawsuit puts your rights at risk.
Have you received a letter or call from Resurgent Capital Services? Share your experience or questions in the comments to help other consumers understand what to check before responding.