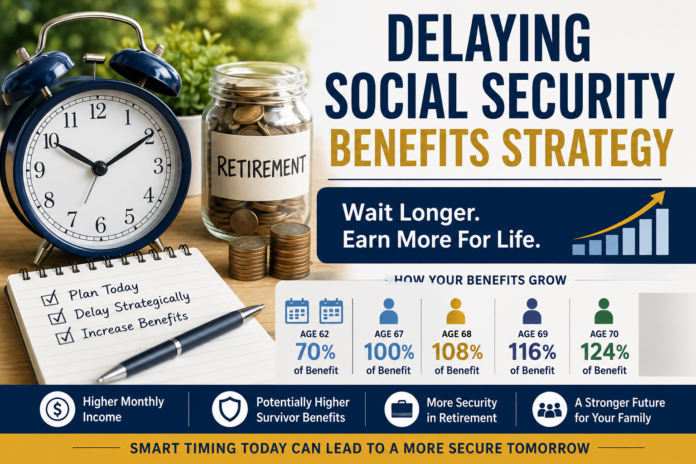

The delaying social security benefits strategy continues to attract attention among U.S. retirees because waiting to claim retirement benefits can result in a permanently larger monthly payment. Under current Social Security rules, eligible workers may begin retirement benefits at 62, but claiming before full retirement age reduces the monthly amount. Workers who wait beyond full retirement age can earn delayed retirement credits until age 70.
For people born in 1960 or later, full retirement age is 67. A worker who waits until 70 can receive 124% of the benefit available at full retirement age. That increase can make the timing of Social Security a major retirement-income decision, particularly for workers who have other sources of income available while they wait.
The latest 2026 Social Security figures also provide important context. The annual cost-of-living adjustment for 2026 is 2.8%, while the maximum amount of earnings subject to Social Security payroll tax increased to $184,500. Meanwhile, the latest Trustees Report continues to project significant long-term financial challenges for the program.
What It Means to Delay Social Security
Social Security retirement benefits are not the same at every claiming age.
A worker can generally start retirement benefits at 62, but an early claim permanently reduces the monthly retirement benefit. Full retirement age provides the worker’s unreduced benefit, while delaying after full retirement age can increase the payment through delayed retirement credits.
For people born in 1960 or later, the current percentages are:
| Claiming age | Benefit as a percentage of full retirement benefit |
|---|---|
| 62 | 70% |
| 63 | 75% |
| 64 | 80% |
| 65 | 86.7% |
| 66 | 93.3% |
| 67 | 100% |
| 68 | 108% |
| 69 | 116% |
| 70 | 124% |
These percentages apply to workers whose full retirement age is 67.
The most important point is that delaying beyond full retirement age does not merely postpone the payment. It increases the monthly benefit that the worker can receive for the rest of retirement.
Why Age 70 Matters
Age 70 is the endpoint for delayed retirement credits.
For workers born in 1943 or later, Social Security provides delayed retirement credits equal to 8% for each full year of delay after full retirement age. Credits accumulate for eligible months and stop once the worker reaches 70.
There is therefore no additional delayed-retirement increase for waiting from 70 to 71.
For someone with a full retirement age of 67, the difference between claiming at 67 and claiming at 70 is significant. The worker receives 100% of the calculated full-retirement-age benefit at 67 and 124% at 70.
The larger payment continues rather than disappearing after the first year.
That feature is one reason many retirement-planning discussions focus on age 70 as the latest useful claiming point.
The Dollar Difference Depends on Your Earnings Record
Social Security does not give every retiree the same monthly benefit.
The amount depends primarily on the worker’s earnings history and Social Security record. As a result, a percentage increase can translate into very different dollar amounts for different households.
The maximum retirement benefit illustrates the difference.
For 2026, a worker who earned the taxable maximum in every year beginning at age 22 and claims benefits at age 62 can receive a maximum monthly retirement benefit of $2,969.
The maximum is $4,152 at full retirement age and $5,181 at age 70.
Most retirees do not qualify for these maximum amounts.
Still, these figures demonstrate why claiming age matters. The percentage applied to a worker’s calculated benefit can create a substantial difference in monthly retirement income.
Full Retirement Age Determines When the Rules Change
Full retirement age is a critical part of any Social Security claiming decision.
The age depends on the worker’s birth year. It gradually increased under federal law and reached 67 for people born in 1960 and later.
A worker who claims before full retirement age receives a reduced benefit. A worker who claims at full retirement age receives the full calculated retirement benefit. A worker who continues to wait after that age can earn delayed retirement credits.
This creates three distinct claiming periods:
- Before full retirement age: Monthly benefits are permanently reduced.
- At full retirement age: The worker receives 100% of the calculated benefit.
- After full retirement age through age 70: Eligible workers can earn delayed retirement credits.
Understanding these stages is essential because the financial consequences differ significantly.
Working While Delaying Social Security
Employment can change the timing decision.
Some workers continue earning income after reaching their early 60s. If they claim Social Security before full retirement age while continuing to work, the retirement earnings test may reduce benefits temporarily.
In 2026, the annual earnings limit for someone who is younger than full retirement age throughout the year is $24,480.
Social Security withholds $1 in benefits for every $2 earned above that limit.
For someone who reaches full retirement age in 2026, a higher earnings limit of $65,160 applies to earnings received before the month the worker reaches full retirement age. Social Security withholds $1 for every $3 earned above that limit.
Once the worker reaches full retirement age, the earnings limit no longer applies.
The earnings test does not mean that a person permanently loses every dollar withheld. Social Security adjusts the benefit at full retirement age to account for months when benefits were withheld because of excess earnings.
For workers who plan to remain employed, these rules can make delaying benefits especially relevant.
Additional Work Can Also Affect the Benefit Calculation
Delaying Social Security often occurs alongside continued employment.
That can create another potential benefit because Social Security uses a worker’s earnings record when calculating retirement benefits.
The retirement benefit calculation generally uses the worker’s highest 35 years of indexed earnings. If someone works additional years and earns more than they did in one of the years already included, the newer earnings can replace a lower year.
However, simply working longer does not automatically produce a higher benefit for everyone.
The effect depends on the worker’s existing earnings history.
Someone with fewer than 35 years of covered earnings may also see a different result because years without earnings can affect the benefit calculation.
Therefore, workers should review their individual Social Security earnings record rather than assume that another year of employment will produce a specific increase.
Medicare Is a Separate Decision
One of the most important details for people delaying retirement benefits involves Medicare.
Choosing to delay Social Security does not automatically mean a person should delay Medicare.
People approaching age 65 need to understand their Medicare enrollment obligations and whether they qualify for a special enrollment period based on current employment and employer coverage.
This distinction matters because Social Security retirement benefits and Medicare have different enrollment rules.
Someone may decide to postpone Social Security until 70 while still taking the appropriate steps for Medicare at 65.
Workers who are approaching Medicare eligibility should examine their individual circumstances before deciding when to enroll.
Marriage Can Change the Calculation
Social Security claiming decisions can have consequences for both spouses.
A spouse may qualify for a benefit based on the other spouse’s work record. However, delaying the higher earner’s retirement benefit does not simply increase a spouse’s benefit to 50% of the higher earner’s age-70 payment.
Spousal benefits generally use the worker’s full-retirement-age benefit as the basis for the maximum spousal amount.
Delayed retirement credits can nevertheless matter when considering survivor benefits.
This distinction is particularly important for married couples because the claiming decision of one spouse can affect the household’s future income.
A higher earner’s decision to delay may provide a larger retirement benefit for that worker and potentially a larger survivor benefit for a qualifying surviving spouse.
Survivor Benefits Deserve Special Attention
Retirement planning should not stop with the worker’s own monthly benefit.
Social Security rules allow delayed retirement credits earned by a worker to affect certain survivor benefits.
That can make the claiming decision especially important when one spouse has a significantly larger Social Security benefit than the other.
For example, a household may evaluate not only how much income the higher earner receives during retirement but also what benefit could remain available to the surviving spouse.
This is one reason a married couple should evaluate Social Security as a household decision rather than viewing each person’s claim in isolation.
The rules surrounding survivor benefits are different from ordinary retirement benefits, so the two should not be treated as interchangeable.
How the 2026 Social Security Update Fits Into the Decision
The current program environment is another factor retirees are watching.
The 2026 Trustees Report projects that the combined Social Security trust funds will be depleted in 2034 under the report’s intermediate assumptions.
If Congress makes no changes to the program, continuing income at that point would cover about 83% of scheduled benefits.
The report also projects depletion of the Old-Age and Survivors Insurance trust fund in the fourth quarter of 2032. Continuing income would cover about 78% of scheduled OASI benefits after depletion under the report’s assumptions.
These are projections, not current reductions in benefits.
The existing Social Security claiming rules remain in effect.
The trust fund projections also do not eliminate delayed retirement credits under current law.
Retirees should therefore distinguish between today’s rules and potential future legislative changes.
Should Everyone Wait Until 70?
No single claiming age is appropriate for every American.
Waiting until 70 produces a larger monthly benefit, but a worker who delays also gives up the payments that could have been collected earlier.
The value of waiting therefore depends partly on how long the retiree ultimately receives benefits and what other retirement income is available during the waiting period.
Health and longevity expectations can also influence the decision.
Someone who needs Social Security income immediately may have a different priority from someone who has sufficient income from employment, savings, pensions or other sources.
The purpose of delaying is not simply to maximize the monthly check. It is to determine whether a larger guaranteed monthly payment later provides greater value for the individual’s retirement plan.
Using Your Personal Social Security Estimate
Generic examples can explain the rules, but a personal Social Security estimate provides more useful information.
Workers can access their Social Security information online and review estimated retirement benefits at different claiming ages.
The estimate can help answer several practical questions:
- What is the estimated benefit at 62?
- What is the estimated benefit at full retirement age?
- What would the benefit be at 70?
- How would additional earnings affect the record?
- Does continued employment create an earnings-test issue?
- How much income is available while waiting?
The answers will differ from person to person.
The maximum Social Security benefit figures often receive attention, but they apply only to workers with exceptionally high and consistent taxable earnings histories.
For most retirees, the personalized estimate is much more relevant.
A Practical Way to Evaluate Delayed Claiming
Workers considering a delay can start by identifying their full retirement age.
Next, they can compare their estimated benefits at 62, full retirement age and 70.
The next step is to determine whether they have enough income to cover the period before claiming.
For someone still working, employment income may provide that bridge. For another household, savings or a pension may fill the gap.
Married workers should then evaluate the potential impact on the spouse and survivor benefits.
Medicare should be considered separately.
Finally, the worker should review the latest Social Security rules and personal benefit estimate before making a final decision.
This process provides a more realistic picture than focusing only on the headline percentage increase.
The Main Advantages of Waiting
The strongest argument for delayed claiming is the permanent increase in monthly retirement income.
For people born in 1960 or later, waiting from full retirement age at 67 to age 70 raises the benefit from 100% to 124%.
Other potential advantages include:
- A larger monthly Social Security payment.
- A larger benefit that may continue for life.
- Potentially higher survivor benefits in qualifying circumstances.
- More time for additional earnings to affect the worker’s earnings record.
- The opportunity to continue working while postponing Social Security income.
These advantages must be weighed against the loss of earlier payments.
Important Limits to Remember
Several limits should remain at the center of the decision.
First, delayed retirement credits stop at age 70.
Second, Social Security does not calculate every retiree’s benefit from the same dollar amount.
Third, continuing to work does not automatically guarantee a higher retirement benefit.
Fourth, delaying Social Security does not mean Medicare should automatically be delayed.
Finally, future changes to Social Security law remain possible because the program faces a long-term financing shortfall.
These factors make personal planning more important than relying on a simple rule such as “always claim early” or “always wait until 70.”
What the Current Rules Mean for Retirees
The fundamental Social Security claiming framework remains clear in 2026.
Eligible workers can generally claim retirement benefits beginning at 62. Claiming before full retirement age reduces the monthly benefit. Full retirement age provides the unreduced amount, while eligible workers can earn delayed retirement credits after full retirement age through age 70.
For workers born in 1960 or later, the difference is particularly straightforward: 70% at age 62, 100% at age 67 and 124% at age 70.
The latest 2026 figures do not change that structure.
The 2.8% COLA has increased Social Security payments for 2026, while the maximum taxable earnings amount and retirement earnings-test thresholds have also risen.
At the same time, the 2026 Trustees Report shows that Social Security’s long-term financing challenge remains unresolved.
That combination makes accurate retirement planning increasingly important.
Bottom Line
The best way to evaluate delaying Social Security is to look beyond the question of whether a larger check sounds attractive.
The more useful question is whether waiting fits the retiree’s complete financial situation.
Workers should compare their personal benefit estimates, understand their full retirement age, account for employment income and review potential spouse and survivor implications. They should also handle Medicare separately and remain aware of changes to Social Security law.
For people born in 1960 or later, current law provides a substantial incentive to wait after full retirement age: the retirement benefit can rise from 100% at 67 to 124% at 70.
That increase can provide valuable lifetime income, particularly for retirees who can comfortably cover their expenses while waiting.
However, the decision remains personal. The strongest retirement strategy is one based on the worker’s actual Social Security record, household income needs and long-term financial objectives.
Are you planning to claim Social Security early, at full retirement age, or wait until 70? Share your thoughts and stay informed about the latest Social Security changes.