
Can credit card companies garnish your wages? Yes, credit card companies can garnish wages in many U.S. states after obtaining a court judgment and completing the required legal procedures. However, missing credit card payments does not automatically allow a creditor to take money from your paycheck. Federal law limits wage garnishment for ordinary consumer debts, and some states provide additional protections for people facing financial hardship.
Wage garnishment can make it harder to pay rent, utilities, groceries, and other essential expenses. For consumers struggling with credit card debt, understanding the legal process is an important step toward protecting their income.
The rules depend on where you live, how much you earn, and whether a creditor has obtained a judgment against you. Knowing what creditors can and cannot do may help you respond before an unpaid balance turns into a more serious financial problem.
Can Credit Card Companies Garnish Your Wages Without a Court Judgment?
Generally, no. A credit card company cannot simply contact your employer and demand money from your paycheck because you have missed payments.
For ordinary credit card debt, the creditor generally must file a lawsuit and obtain a court judgment before pursuing wage garnishment. It must then follow the applicable state procedures to enforce that judgment.
The process usually involves several stages:
- Missed payments: Your credit card account becomes delinquent when you fail to make the required payments.
- Collection attempts: The creditor or a collection agency may contact you to request payment.
- Lawsuit: The creditor may file a case seeking repayment of the outstanding balance.
- Court judgment: The court may enter a judgment if the creditor proves its claim or you fail to respond appropriately.
- Garnishment proceedings: The creditor follows the required legal process to seek payment from your earnings.
- Employer withholding: Your employer withholds the legally authorized amount after receiving the appropriate documents.
Not every delinquent account results in a lawsuit. Some creditors offer repayment plans, accept settlements, or continue other lawful collection efforts.
However, ignoring a court summons can increase the risk of a default judgment. Once a creditor obtains a judgment, it may have additional ways to collect the debt.
How Much Can Credit Card Companies Take From Your Paycheck?
Federal law places limits on wage garnishment for ordinary consumer debts, including unpaid credit card balances.
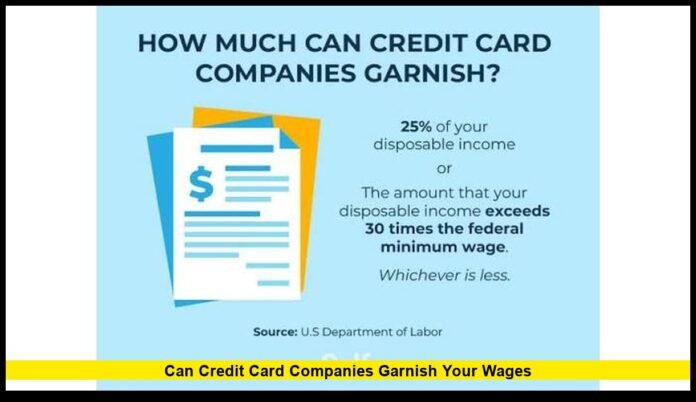
Under the general federal rule, a creditor cannot garnish more than the smaller of:
- 25% of your disposable earnings, or
- The amount by which your disposable earnings exceed 30 times the federal minimum hourly wage for the applicable pay period.
Disposable earnings generally refer to the money remaining after deductions required by law, such as applicable taxes. Voluntary deductions do not necessarily reduce the amount used to calculate the garnishment limit.
The second calculation provides additional protection for workers with lower earnings. If your disposable earnings fall below the applicable threshold, federal law may prevent garnishment for ordinary consumer debt.
Example of Wage Garnishment for Credit Card Debt
Suppose your disposable earnings total $800 per week.
Twenty-five percent of $800 is $200.
The second calculation uses 30 times the federal minimum wage of $7.25 per hour, resulting in a weekly threshold of $217.50. Subtracting $217.50 from $800 leaves $582.50.
Because $200 is the smaller amount, the general federal limit would allow a garnishment of up to $200 per week in this example.
This is an illustration of the federal maximum, not a guarantee that a creditor will collect that amount. State law may provide stronger protections, and the actual withholding must comply with the applicable legal order.
Important: The federal limit is not an automatic deduction. A creditor must still satisfy the legal requirements for garnishment before an employer can withhold money.
Can Credit Card Companies Take Your Entire Paycheck?
For ordinary credit card debt, federal law generally prevents creditors from taking an entire paycheck through wage garnishment.
The applicable limits protect a portion of disposable earnings, while state laws may offer additional safeguards for workers with limited income.
However, different rules can apply to certain other obligations, including child support and some tax debts. Those rules should not be confused with the requirements governing ordinary credit card debt.
A creditor with a judgment does not gain unrestricted access to your earnings. It must follow the law and comply with the applicable garnishment limits.
If you believe your employer has withheld too much money, review the garnishment documents and pay stubs. You may be able to challenge an incorrect calculation or claim an exemption under state law.
Do State Laws Affect Credit Card Wage Garnishment?
Yes. State law can significantly affect whether and how much a creditor can garnish from your wages.
Federal law establishes general limits, but states can provide greater protection. State rules may also determine the forms creditors must file, how employers process garnishments, and which income exemptions are available.
For example, Washington generally protects the greater of 80% of disposable earnings or an amount calculated using 35 times the state minimum hourly wage for consumer debt garnishments, subject to applicable statutory requirements.
Other states use different calculations and exemptions. As a result, a creditor may be legally permitted to collect a certain amount in one state but be restricted to a smaller amount in another.
Before accepting a creditor’s calculation, check the garnishment rules that apply to your state. Do not assume that the federal 25% maximum automatically determines how much your employer can withhold.
Can Credit Card Companies Garnish Your Bank Account?
Yes. A creditor that has obtained a judgment may be able to pursue a bank account garnishment or levy under applicable state law.
Bank account garnishment differs from wage garnishment because it targets eligible funds already held in a financial institution.
Depending on the legal order, a bank may have to freeze funds or turn over money to satisfy the judgment. This can temporarily limit your access to money needed for ordinary living expenses.
However, creditors cannot necessarily collect every dollar in an account. Certain benefits and other funds may receive legal protection.
Social Security benefits, for example, generally receive federal protection from private creditors collecting ordinary credit card debt. Other exemptions may apply under federal or state law.
If your bank account contains protected benefits, keep records of deposits and benefit statements. These documents may help establish which funds qualify for protection.
If your account is frozen unexpectedly, ask the bank for information about the legal order and act promptly to determine whether you can claim an exemption.
Can Credit Card Companies Garnish Social Security or Disability Benefits?
Generally, private credit card companies cannot garnish Social Security benefits to collect ordinary credit card debt. Supplemental Security Income, or SSI, also receives strong federal protection from private debt collection.
These protections are particularly important for people who depend on benefits to cover housing, food, medical expenses, and other necessities.
However, the rules governing benefits deposited into bank accounts can differ from those governing benefits before deposit. Federal rules require banks to protect certain qualifying electronically deposited benefits, generally covering up to two months of specified federal benefit payments automatically.
Additional protections may apply depending on the type of income and the circumstances.
Certain exceptions exist for specific obligations, such as qualifying government debts and some family support orders. Those exceptions do not give ordinary credit card companies unrestricted access to protected benefits.
If a creditor attempts to collect money you believe is exempt, seek clarification from the bank or a qualified attorney. You may need to follow a specific legal process to protect the funds.
What Happens If You Ignore a Credit Card Debt Lawsuit?
Ignoring a credit card lawsuit can increase the risk of wage garnishment and other collection actions.
When a creditor files a lawsuit, the court documents generally explain how to respond and provide information about deadlines. If you fail to respond, the creditor may ask the court to enter a default judgment.
A default judgment can give the creditor additional legal options for collecting the unpaid balance.
Depending on state law, the creditor may pursue wage garnishment, seek eligible funds in a bank account, or use other permitted enforcement methods.
Failing to respond can also make it harder to challenge the amount claimed or raise valid defenses.
If you receive a lawsuit, take these steps:
- Read the court documents and identify the response deadline.
- Check whether the account and claimed balance are accurate.
- Gather payment records, account statements, and relevant correspondence.
- Submit a timely response if required.
- Contact a consumer law attorney or legal aid organization if you need assistance.
Responding to a lawsuit does not automatically mean you admit owing the debt. It gives you an opportunity to raise appropriate defenses and require the creditor to establish its claim.
How Can You Stop or Reduce Wage Garnishment?
Depending on your circumstances, you may have several options to challenge or reduce a credit card wage garnishment.
Claim an exemption: State law may protect part of your income or certain types of benefits. You may need to file paperwork and provide evidence of your financial circumstances.
Challenge an improper garnishment: You may be able to challenge the action if the creditor failed to follow the required procedures, the amount exceeds legal limits, or protected income is involved.
Negotiate a payment arrangement: Some creditors may agree to a repayment plan or settlement. Get the terms in writing and clarify whether the agreement changes or suspends the existing garnishment.
Seek legal assistance: Consumer law attorneys and legal aid organizations can help you understand available exemptions and determine whether the creditor has followed the law.
Explore bankruptcy options: Bankruptcy may provide relief for some people facing overwhelming unsecured debt. The effect on an existing garnishment depends on the circumstances and applicable bankruptcy rules. Obtain qualified legal advice before deciding whether to file.
Act quickly when you receive a garnishment notice. Deadlines for challenging an order or claiming an exemption may be short.
Can Your Employer Fire You Because of Credit Card Wage Garnishment?
Federal law provides certain employment protections for workers whose earnings are garnished.
Under the Consumer Credit Protection Act, an employer generally cannot discharge an employee because the employee’s earnings have been garnished for one debt.
However, this federal protection does not provide the same blanket restriction when garnishment involves a second or subsequent debt. State law may provide additional safeguards.
Employers must also follow applicable withholding requirements. A garnishment order does not authorize them to take an arbitrary portion of your paycheck.
If you believe your employer has retaliated against you because of a garnishment, consider seeking guidance from the U.S. Department of Labor or an employment attorney.
How Long Can Credit Card Wage Garnishment Last?
There is no single nationwide time limit that applies to every credit card wage garnishment.
The duration depends on the amount of the judgment, the amount collected from each paycheck, applicable interest and costs, and state law.
Garnishment may continue until the creditor collects the amount permitted under the judgment or the order ends through a legal process.
Some states also establish deadlines for enforcing judgments and rules for renewing them. These requirements vary by jurisdiction.
Keep copies of your pay stubs, court documents, payment records, and garnishment notices. Reviewing these records can help you track the balance and identify potential errors.
If deductions continue after the judgment has been satisfied, contact the court or a qualified attorney to determine the appropriate next step.
What Should You Do If a Credit Card Company Threatens Wage Garnishment?
First, determine whether the creditor is warning about a possible lawsuit or whether a court has already entered a judgment.
A collection representative may say that garnishment is possible, but a threat alone does not establish that the creditor has legal authorization to take money from your paycheck.
For ordinary credit card debt, creditors generally must obtain a judgment and complete the required legal procedures before garnishing wages.
If you receive a garnishment threat, consider these steps:
- Request written information about the debt and the party collecting it.
- Review any legal notices or court documents.
- Keep records of payments and collection communications.
- Check your state’s garnishment limits and exemptions.
- Do not ignore court deadlines.
- Seek legal assistance if you are sued or receive a garnishment order.
You may be able to negotiate with the creditor before a judgment is entered. If you reach an agreement, make sure it clearly explains the payment terms and how the creditor will handle further collection efforts.
Frequently Asked Questions About Credit Card Wage Garnishment
Can credit card companies garnish your wages after one missed payment?
No. One missed payment does not automatically authorize garnishment. A creditor generally must obtain a court judgment and complete the required legal procedures.
Can a credit card company garnish wages without notifying you?
Creditors must follow applicable court and notice procedures. If you discover an unexpected garnishment, request the judgment and garnishment documents to determine whether the legal requirements were met.
Can a credit card company garnish wages if you are unemployed?
An employer cannot garnish wages you are not earning. However, a creditor with a judgment may have other lawful collection options, depending on your assets, income, and state law. Certain benefits may be exempt.
Can a credit card company garnish more than 25% of your paycheck?
Federal law generally limits garnishment for ordinary consumer debt to the lesser of 25% of disposable earnings or the amount exceeding the applicable minimum-wage threshold. State law may provide greater protection. Other debt categories may follow different rules.
Can you settle credit card debt after a judgment?
Yes. A creditor may agree to settle a judgment debt or accept payments under a negotiated arrangement. Get the terms in writing and clarify how the agreement affects any existing garnishment.
Does changing jobs stop wage garnishment?
Changing jobs does not eliminate the underlying judgment. A creditor may be able to pursue garnishment through your new employer after following the required procedures.
Final Thoughts on Credit Card Wage Garnishment
Credit card companies can garnish wages in many U.S. states, but they generally must obtain a court judgment and comply with federal and state law before taking money from your paycheck. Federal limits restrict the amount creditors can collect, while state exemptions may offer additional protection for people experiencing financial hardship.
If you are struggling with credit card debt, do not assume that garnishment is inevitable. Review legal notices carefully, understand your rights, and consider negotiating with the creditor or seeking qualified legal assistance.
Have you experienced a credit card debt lawsuit or wage garnishment? Share your thoughts in the comments and stay informed about your consumer debt rights.